Guide
Cost of Buying Property in Ibiza & Taxes (2026 Guide)
Published Updated 17 minutes to read
This guide explains the real costs and taxes of buying, owning, renting and selling property in Ibiza, especially for non-resident buyers.
Last updated: November 2026.
In short
- Buying a resale home: plan for about 9% to 13% on top of the price. Most of it is transfer tax (ITP), from 8% to 13% depending on the price, plus notary, registry and your lawyer.
- Buying a new build from a developer: 10% VAT plus 1,5% stamp duty (2% from €1.000.000), plus notary, registry and your lawyer.
- Owning a second home: the yearly IBI (0,40% to 0,69% of the cadastral value in most municipalities), non-resident income tax on an imputed income, waste collection and, above €3.000.000 per person, wealth tax.
- Renting out: 19% (EU/EEA) or 24% (outside the EU/EEA) non-resident income tax. From 1 December 2026, stays of 30 nights or fewer also carry 10% VAT.
- Selling: 19% capital gains tax for all non-residents. The buyer withholds 3% of the price, and the seller pays the municipal plusvalía.
1. Introduction
You are exploring the idea of buying a house in Ibiza, which comes with the idea of fully enjoying the Ibiza lifestyle, with its gastronomy, sports, long lunches on the beach with friends… But there is also the formal side to organizing this all… The paperwork, and… taxes! You obviously want to understand what the cost is of buying and owning property on the white island.
To keep things simple, you pay taxes when you buy, while you own, if you rent out and eventually, when you want to sell your property. We are here to provide you with a clear overview of all types of taxes, and as it might be complicated at times, we are also providing real-life examples. You will know exactly what you will pay in local property taxes (IBI), and if renting, how much of your rental income you will keep after non-resident tax (IRNR), and which costs are deductible. Be prepared for the capital gains when selling, and the municipal plusvalía. All clear…
In Ibiza – which is part of the Balearics – some taxes are decided regionally. Transfer tax, wealth tax, inheritance and gift tax are just examples that can differ from other parts of Spain. For example, buying a villa in Santa Eulalia is not the same fiscally as buying an apartment in Barcelona. Local rules (legalities) and local taxes…
Where you come from (EU or NON-EU), will also affect taxation. EU and EEA residents benefit from certain reductions and can deduct expenses against rental income. Non-European buyers, on the other hand, face higher rates and different paperwork.
Legal checks and compliance are always handled by an independent lawyer. Our role is to coordinate the process, explain what matters, align timelines, and connect you with the right local experts, so nothing is missed and everything stays clear.
2. What taxes do you pay when buying property in Ibiza?
Almost there… a beautiful finca, sleek new build penthouse or a property to renovate… What taxes will you pay on acquisition of this property?
2.1 What do you pay on a new build: VAT (IVA) and stamp duty (AJD)?
If you are buying a brand-new property directly from a developer, you pay VAT instead of transfer tax. The rate is 10% for residential homes, 4% for officially protected housing, and 21% for extras like parking spaces sold separately. On top of that comes stamp duty (Actos Jurídicos Documentados, AJD): 1,5% in the Balearics, or 2% for properties of €1.000.000 or more. This is the tax for formalising your purchase in a public deed and registering it.
When buying a property it is most of all important to know who you are buying it from. Will you be the first owner? How is the property sold? Find here an overview of the kind of transfer tax (ITP) or VAT you will be facing.
| Asset type | New / first delivery | Second-hand / resale | VAT rate (if VAT) | Key notes |
|---|---|---|---|---|
| Apartment / villa (residential) | VAT (first delivery) | ITP (default) | 10% (4% if VPO) | First delivery of a newly built home = VAT. Resale = ITP (no VAT). |
| Urban building plot (solar) | VAT (when the seller acts as an entrepreneur) | ITP (private seller) | 21% | Buildable land sold by an entrepreneur carries VAT; private to private is usually ITP. |
| Rustic land (no building use) | Usually ITP (VAT-exempt) | ITP | – | Non-buildable rural land is generally VAT-exempt, so ITP applies. |
| Parking space sold with the home (same deed, up to 2 spaces) | VAT (follows the home) | ITP | 10% (with the home) | Must be in the same building and deed as the home to get the housing VAT rate. |
| Parking space sold on its own | VAT (first delivery) | ITP | 21% | Stand-alone parking: 21% VAT when new; ITP on resale. |
| Commercial unit / office | VAT (first delivery) | ITP (default) | 21% | Second-hand is VAT-exempt by default, so ITP, unless the VAT exemption is waived. |
2.2 How much is the property transfer tax (ITP)?
For resale properties (second-hand homes), VAT doesn’t apply. You will pay the property transfer tax (ITP), which is:
- 8% for the part up to €400.000
- 9% for the part between €400.000 and €600.000
- 10% for the part between €600.000 and €1.000.000
- 12% for the part between €1.000.000 and €2.000.000
- 13% for the part over €2.000.000
Important note: the tax base for the transfer tax is either the valor de referencia catastral (VRC) or the sale price of the property, whichever is higher. The tax office sets the VRC to prevent undervalued sales. It is not the same as the valor catastral, which is used for your yearly taxes and is usually much lower than the market value of the property.
2.3 What is the plusvalía municipal (IIVTNU)?
What is Plusvalía in Ibiza?
A municipal tax on the increase in land value since the last transfer of an urban property. Collected by the five Ibiza town halls (Eivissa, Santa Eulària, Sant Josep, Sant Antoni, Sant Joan).
Who pays the plusvalía municipal?
Typically, the seller. If the seller is non-resident, buyers usually include a retention/escrow in the deed. This retention will be released once proof of filing and payment is provided.
How it’s calculated (use the lower result):
- Objective method (coefficients): council coefficients applied to the cadastral land value and years held.
- Real-gain method: applies to any urban property (not just bare land).
Formula: (Sale price − Purchase price) × Land % (from the cadastral record). If the result is zero or less, there is no tax.
From 1 December 2026, new coefficients apply to the objective method. Always compare both methods and use the lower result.
What to check before signing
Ask your advisor to model both methods (objective vs. real-gain). Confirm the cadastral split (land vs. building); this drives both methods.
Add clear deed wording: seller liable, retention if non-resident, and timing for releasing funds on proof of payment.
Eivissa: town hall calculator
Sant Antoni de Portmany: ATIB calculator
Sant Joan de Labritja: ATIB calculator
2.4 How much are notary and registry fees?
For a straightforward cash purchase, budget about 0,3% to 0,6% of the price for the notary, the registry and the administration (gestoría). Add translation, power of attorney or mortgage extras if relevant.
Notary and registry fees
- Notary (escritura de compraventa): regulated fee scale. For standard deeds in Ibiza, expect ~€800–€1.800 (more pages = higher fee; bilingual deeds add pages).
- Property Registry (Registro): ~€400–€1.200, depending on price and deed complexity.
- Gestoría (administration/filing): ~€300–€600 for handling settlements, filings and final reconciliations.
2.5 What does a mortgage cost?
When applying for a mortgage, the bank will always provide you with a full offer including all costs.
Since the 2019 mortgage law, banks are covering part of the cost and costs are divided as follows:
- Paid by the bank (by law): Notary fee for the mortgage deed, Property Registry inscription of the mortgage, gestoría/admin, and the stamp duty (AJD) on the mortgage.
- Paid by you:
- Valuation (tasación) ~€300-600 and,
- Any copies of the mortgage deed you request which are max €100.
- If applicable, opening fees (comisión de apertura). This is not mandatory but can go up to 2%. Always check your FEIN (the offer from the bank).
Note: The purchase deed’s costs (notary/registry of the sale) are separate from the mortgage and are typically paid by the buyer; the items above refer only to the mortgage deed.
Early-repayment fines (by law)
If you decide to repay your mortgage before the agreed period, the “fines” are limited by law and those can be as follows:
- Variable-rate mortgages: bank may choose one regime; 0,25% in the first 3 years or 0,15% in the first 5 years; after that, 0%.
- Fixed-rate mortgages: up to 2% in the first 10 years, then up to 1.5% thereafter, only if the bank incurs a proven financial loss.
3. What taxes do you pay while owning property in Ibiza?
You want the cost of your new property to be predictable. Here is a short overview of all the cost that you should account for.
3.1 How much is the annual property tax (IBI)?
The municipal tax is calculated based on the cadastral value which you can take from the municipal property tax (“Impuesto sobre Bienes Inmuebles” – IBI) receipt. This IBI is usually much lower than the market value, much lower. However, each property is different and It’s not a flat % of market. The town hall applies its municipal rate to the cadastral base shown on the IBI bill.
How to calculate the IBI?
Use your latest IBI receipt (or Catastro extract). You will only need two items: the base liquidable and the IBI rate (tipo) of your municipality.
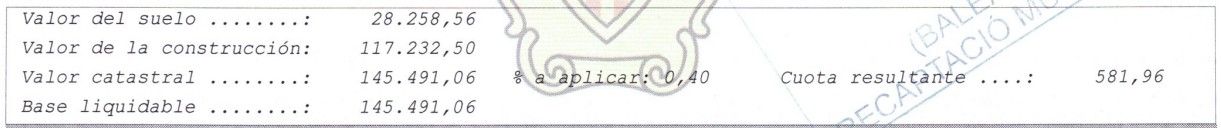
| Item (Spanish) | Amount |
|---|---|
| Land value (Valor del suelo) | €28.258,56 |
| Building / construction value (Valor de la construcción) | €117.232,50 |
| Cadastral value — land + building (Valor catastral) | €145.491,06 |
| Taxable base (Base liquidable) | €145.491,06 |
| Rate to apply (Tipo a aplicar) | 0,4% |
| Resulting amount / tax due (Cuota resultante) | €581,96 |
The calculation for the IBI is as follows: Taxable base × Rate = €145.491,06 × 0,4% = €581,96.
What are the IBI rates applied by the local governments?
Here are the current IBI (property tax) rates on Ibiza, by municipality, and if available per property as well.
| Municipality | Urban IBI 2025 | Differentiated rate | Rural (rústico) | BICES |
|---|---|---|---|---|
| Eivissa (Ibiza town) | 0,69% | 0,73% | n/a | n/a |
| Santa Eulària des Riu | 0,40% | n/a | 0,45% | n/a |
| Sant Josep de sa Talaia | 0,40% | 0,55% | 0,30% | 1,30% |
| Sant Antoni de Portmany | 0,68% | n/a | 0,72% | 0,60% |
| Sant Joan de Labritja | 0,63% | 0,73% | 0,63% | 1,30% |
- “Urban” applies to most apartments, villas and townhouses.
- “Differentiated rate” covers differentiated rates for either non-residential or top-value leisure/hospitality sectors.
- “Rural/Rústico” is for rural properties/land. Many villas in the campo fall in this category.
- “BICES” applies to properties with special characteristics (industrial/commercial).
Is the IBI tax deductible?
The IBI is also a deductible expense if you rent out your property. The IBI is calculated (and liable) on the 1st day of each year, but it becomes due to pay half way the year in August.
3.2 What is the non-resident income tax (IRNR) on a second home?
If you don’t rent your property, Spain imputes a small fictional income on second homes. You declare this under IRNR as a non-resident and an example tax calculation is shown below.
What is the rate for non-resident income tax in Ibiza?
Tax rate: the imputed income is 2% of the cadastral value, or 1,1% if the cadastral value was updated in the last 10 years. You pay 19% (EU/EEA) or 24% (outside the EU/EEA) on that amount.
From 2027, Royal Decree-law 29/2026 brings a new scale for this tax, based on the combined cadastral value of your homes. We will update this section once the rates are final.
In the case of the IBI receipt above, the payable non-resident income tax would be:
| Example (IBI receipt above) | Amount |
|---|---|
| Cadastral value | €145.491,06 |
| Imputed income (1,1%) | €1.600,40 |
| Tax at 19% (EU/EEA) | €304,08 |
| Tax at 24% (outside the EU/EEA) | €384,10 |
- The IRNR is the same for each municipality since it is calculated by central government based on cadastral value, not local rates.
- If the property is not in use or is rented at market value, actual rents declared are taxed instead.
3.3 Do you pay wealth tax on a home in Ibiza?
You have worked hard, paid the taxes, and, in the end, you must allocate another part of your wealth to the wealth/solidarity tax. In the Netherlands this tax is known as “vermogensbelasting”, in Germany “Vermögensteuer”. In Spain, it’s called the “Impuesto sobre el Patrimonio”.
Wealth tax is a regional tax, and many regional states provide exemptions for up to 100%. Therefore, Spain (as a national state) has introduced the solidarity tax. Any wealth tax paid in your region reduces the bill for the solidarity tax. In Ibiza, the wealth tax bill will probably exceed the amount of a solidarity tax. This means you will most likely not pay any solidarity tax.
What is the wealth tax in Ibiza for non-resident property owners?
It is an annual tax on net wealth that applies to both residents and non-residents with assets in Spain. Since 2024, the Balearic Islands exempt the first €3.000.000 per person (it used to be €700.000). This lowers the tax for many property owners a lot.
What are the wealth tax rates in Ibiza?
Wealth tax is charged on net wealth above €3.000.000 per person. The amount above €3.000.000 is taxed on the Balearic scale, which starts at 0,28% and rises step by step to 3,45% for the part above about €10,9 million.
- €0 on net wealth up to €3.000.000 per person
- Above €3.000.000: the Balearic scale on the amount above it, from 0,28% up to 3,45%
An example:
Below you find a few examples. Do you own or plan to buy an apartment of €700.000? You will be fully exempt. Buying a high-end home of €4.000.000 together with your partner, 50/50? You will not pay this tax. Buying the same home on your own, without a mortgage? About €1.000.000 is taxable, which comes to roughly €7.500 a year.
| Home value | Ownership | Balearic wealth tax | Solidarity tax (extra) | Total per year |
|---|---|---|---|---|
| €700.000 | Single | €0 | €0 | €0 |
| €700.000 | Married (50/50) | €0 | €0 | €0 |
| €4.000.000 | Single | €7.473 | €0 | €7.473 |
| €4.000.000 | Married (50/50) | €0 | €0 | €0 |
| €10.000.000 | Single | €145.445 | €0 | €145.445 |
| €10.000.000 | Married (50/50) | €47.043 | €0 | €47.043 |
Per year, for a home without a mortgage and no other assets in Spain.
The table also shows the solidarity tax. The wealth tax you pay in the Balearics is deducted from it, so in all these cases you only pay the Balearic wealth tax.
How can I minimize wealth tax on my Spanish property?
You might have been in touch with a wealth planner or someone that organizes your strategic personal finance. It’s good to review your strategy with your advisor before buying a property in Ibiza. However, below you will find some common practices to reduce your exposure.
- Be married to someone.
- Strategy: Hold assets jointly with spouse to double exemptions
- Benefit: €6.000.000 combined exemption vs. €3.000.000 for singles
- Example: a €4.000.000 property owned 50/50 = €0 tax, against about €7.500 if owned by one person (see the example above)
2. Strategic use of debt/mortgages
- Strategy: even if you do not need a mortgage, one can lower your net wealth
- Benefit: Debt reduces taxable wealth
- Example: €4.000.000 property with €1.000.000 mortgage = €3.000.000 net value and therefore fully exempt.
3. Residency planning
- Strategy: Careful management of tax residency status
- Consideration: Residents taxed on worldwide assets, non-residents only on Spanish assets
- Note: Madrid residents enjoy 100% wealth tax exemption (but solidarity tax still applies)
4. Family wealth planning
- Strategy: Gift assets to your kids using current low gift tax rates
- Benefit: Reduces taxable estate while benefiting from exemptions
- Timing: Act before potential gift tax reforms
Can I own property through a company to avoid wealth tax?
Some buyers structure ownership through a company (Spanish SL or foreign entity) instead of holding real estate directly. The idea is that if the company owns the property, then the individual only owns shares in the company.
Can you avoid paying taxes this way? This depends on the structure of the company. If the company is a Spanish company, the shares are counted towards Spanish assets for your wealth and solidarity tax.
If the company is a foreign company, this company can only avoid paying the wealth and solidarity tax when the Spanish property assets don’t exceed 50% of the total assets of that company. In short, Spain looks “through” the company and will treat you as if you own the property personally.
Direct ownership of Spanish property → always subject to Spanish Wealth Tax / Solidarity Tax.
3.4 Which other local taxes do you pay?
Urban waste fee (Basura)
Separate from the IBI (Impuesto bienes inmuebles). Each council (Eivissa, Santa Eulària, Sant Josep, Sant Antoni, Sant Joan) sets its own urban waste service fee. Expect one bill per property and the window for payments is typically mid-March to end-May.
How much do you pay for urban waste (basura) in Ibiza?
The rates vary per municipality, but will be in the range of €100-300 for property up to 200m2. Larger villas can expect to pay €500-700 per year.
4. What taxes do you pay when renting out the property?
4.1 How is long-term rental income taxed?
When renting property on a long-term basis, you must be aware of the specific tax obligations under Spain’s Non-Resident Income Tax (IRNR) regime as well as the deductions they can apply.
What taxes apply to long-term rental income in Ibiza?
- EU/EEA Owners (fixed tax rate of 19%): The rental income tax is applied to the net rental income. This means the gross rental income minus deductible expenses related to maintaining and managing the property.
- Non-EU owners (fixed tax rate of 24%): the rate is higher, and until 2025 non-EU owners were taxed on the gross rental income. See below what changed in 2025.
How is rental income taxed for EU/EEA owners under IRNR?
Let’s assume that we have a yearly rental income of €30.000 and deductible expenses of €8.750 (below you can find an overview of deductible expenses).
| Owner | Rental income | Deductible expenses | Taxable income | Tax rate | Tax due |
|---|---|---|---|---|---|
| EU/EEA owner | €30.000 | €8.750 | €21.250 | 19% | €4.037,50 |
| Non-EU owner | €30.000 | €8.750 | €21.250 | 24% | €5.100 |
Before July 2025, non-EU owners were not allowed to deduct expenses to lower the taxable income. In July 2025 the court ruled that denying expense deductions to non-EU landlords violated EU treaty freedoms (Article 63 TFEU on free movement of capital) and Spain’s obligations under tax treaties, such as with the US. As from this date the Spanish tax practice is following EU non-discrimination principles and international agreements.
However, the 24% tax rate remains in place for non-EU owners for now because the ruling only addressed deductibility of expenses, not the applicable tax rate. There are ongoing legal cases aimed at reducing the rate to 19%, but until a final decision non-EU owners benefit from deductions but still pay 24%.
What expenses can I deduct from rental income for tax purposes?
When renting out a property in Spain, non-resident taxpayers can deduct certain expenses from their rental income before calculating the taxable income. See here an overview of deductible expenses:
| Deductible expense | Description |
|---|---|
| Depreciation | Depreciation of the building value (not the land), usually around 3% a year, for wear and tear. |
| Interest | Mortgage interest on loans taken to buy or improve the rental property. |
| Repairs | Costs to keep the property in rentable condition (repairs only, not improvements). |
| Local taxes and fees | Property tax (IBI), waste collection (basura) and municipal fees linked to the property. |
| Insurance | Premiums for home insurance on the rental property. |
| Professional services | Fees for property managers, accountants, lawyers and others managing the rental. |
| Utilities | Water, electricity and internet, if paid by the landlord. |
| Community fees | Contributions to the community of owners. |
Important considerations:
- All expenses must be documented with invoices, receipts, contracts, or proofs of payment that clearly relate to the rental property.
- Deductible expenses must be directly linked to rental activity within the tax year; expenses from when the property is not rented typically cannot be deducted.
- Historically, only EU/EEA residents could deduct these expenses on their IRNR tax declaration. However, following a significant court ruling in 2025, non-EU owners can now also deduct these expenses, although the tax rate remains higher for non-EU residents.
- Improvements or capital investments on the property cannot be deducted as expenses but may be added to the base cost of the property for capital gains tax purposes on sale.
4.2 How are short stays and tourist lets taxed?
What do I need to know about short stay / tourist rentals in Ibiza?
If you plan on renting out your property for short stays or tourist rentals, you need to understand the licensing & VAT that apply in 2026 to comply with new regulations and optimize your rental operations.
Do I charge VAT to my guests when renting out my property?
From 1 December 2026, yes, for most tourist lets. Under Royal Decree-law 29/2026, stays of 30 nights or fewer carry 10% VAT, also when you offer no hotel-style services. Until then, these rentals were exempt. Stays of more than 30 nights stay exempt, and so does renting out your own main home. Charging VAT means you need to be registered for VAT in Spain; your tax adviser or gestor arranges this.
- Subrental: if a third party leases the property and sublets it to guests, the sublease income is subject to VAT. Make sure contracts and invoices show the leasing and subleasing structure correctly.
The decree was approved by Congress on 12 November 2026. Check the latest status with your tax adviser before you set your prices.
How much tax do I pay when I rent my property short-term?
| Item | Description | Amount |
|---|---|---|
| Rental income | Total income from renting the property | €100.000 |
| Deductible expenses | Management, IBI, insurance, repairs, utilities | €25.000 |
| Taxable income | Rental income minus deductible expenses | €75.000 |
| Tax rate (EU/EEA owner) | Fixed rate on net rental income | 19% |
| Tax due | Non-resident income tax (IRNR) | €14.250 |
| VAT (stays of 30 nights or fewer, from 1 December 2026) | 10%, charged to guests on top of the rent and paid to the tax office | €10.000 |
Explanation:
- Rental Income: Assume a gross rental income of €100.000 from tourists
- Deductible Expenses: These include:
- Property management cost: €10.000
- Local property tax (IBI): €2.000
- Insurance and maintenance: €3.000
- Utilities paid by landlord: €1.000
- Repairs & professional fees: €9.000
- Total = €25.000 (approximate, actual varies by property and management)
3. Taxable Income: Rental income minus deductible expenses (€100.000 – €25.000 = €75.000).
4. Non-resident income tax (IRNR): for EU/EEA owners the rate is 19% on net rental income, so €75.000 × 19% = €14.250. For non-EU owners the rate is 24%.
5. VAT: from 1 December 2026, stays of 30 nights or fewer carry 10% VAT. On €100.000 of rental income that is €10.000, charged to your guests on top of the rent and paid to the tax office. VAT is separate from IRNR.
6. Stays of more than 30 nights stay exempt from VAT and are only subject to IRNR.
5. What taxes do you pay when selling the property?
5.1 How much capital gains tax do you pay?
When you sell, it is good to know beforehand how much the tax office will take from your profit. Non-residents pay a flat 19% on capital gains, whether they live in the EU or outside it. The 24% rate for non-EU residents applies to rental income, not to the gain on a sale.
How to calculate capital gains?
Plain simple, the calculation is: capital gain = sale price – acquisition value
Find below an overview that shows exactly what can be included to calculate both the purchase price and the sales price.
| Cost | Counts for purchase value | Counts for sale value | Requirement |
|---|---|---|---|
| Notary fees | Yes | Yes | Must be documented |
| Registry fees | Yes | Yes | Land registry costs |
| Legal fees | Yes | Yes | Lawyer and conveyancing costs |
| Estate agent fees | Yes | Yes | Real estate commission |
| Transfer tax (ITP) | Yes | No | For resale properties |
| VAT and stamp duty (AJD) | Yes | No | For new properties |
| Plusvalía | No | Yes | Municipal tax on the land value gain |
| Improvements | Yes | No | Must add value or extend the life of the property |
| Repairs and maintenance | No | No | Not deductible |
| Mortgage interest | No | No | Not deductible |
| Insurance | No | No | Not deductible |
When it comes to improvements or repairs, there are some key differences in how these can be calculated towards the purchase value.
Deductible improvements:
- Adding rooms, terraces, pools
- Installing central heating/air conditioning
- Major renovations that increase property value
- Extensions approved by town hall
- You must have official invoices and permits
Non-deductible repairs (even with invoices, these don’t qualify) :
- Painting & plastering
- Fixing plumbing, electrical issues
- Regular maintenance
- Furnishing costs
Below is an example of a capital gains tax calculation, at the 19% rate that applies to all non-residents.
| Item | Amount |
|---|---|
| Purchase price | €900.000 |
| Transfer tax (ITP, current brackets) | €80.000 |
| Notary, registry and gestoría (0,5%) | €4.500 |
| Legal fees (1%) | €9.000 |
| Total acquisition value | €993.500 |
| Sale price | €1.400.000 |
| Agency fee (5% + 21% VAT) | −€84.700 |
| Plusvalía (estimate) | −€3.000 |
| Net sale proceeds | €1.312.300 |
| Taxable capital gain | €318.800 |
| Capital gains tax (19%) | €60.572 |
5.2 What is the 3% withholding on a sale by a non-resident?
The buyer must withhold 3% of the sale price to cover the capital gains tax you owe. In this example, the buyer withholds €42.000. You then pay the difference, €18.572 (€60.572 − €42.000), with Form (Modelo) 210 within 4 months of completion at the notary.
What do you do if there is no capital gain?
You are entitled to claim back the entire 3% withholding in case you have suffered a capital loss, when you are break-even or when the 3% was more than you actually had to pay in capital gains tax.
The buyer must file the declaration of purchase (for property purchase taxes) within 1 month of completion. You will have 4 months to claim a refund with Form 210. Note that you will need proof of the 3% withheld by the buyer, proof of bank account ownership, purchase/sales deeds and all receipts related to the purchase/sale (as listed above). After filing it can take up to a year before the payment is made. Interest applies after the 6th month of waiting.
5.3 Who pays the plusvalía?
The plusvalia municipal must be paid by the seller. However, we have described this earlier in this article because the buyer has the obligation to pay in the event the seller fails to pay this.
Find more on this topic in 2.3 What is the plusvalía municipal (IIVTNU)?.
This guide is meant to give you a clear, practical overview based on real transactions and current regulations. It does not replace personal tax or legal advice. Your final tax position always depends on your personal situation and should be confirmed by a qualified advisor.